

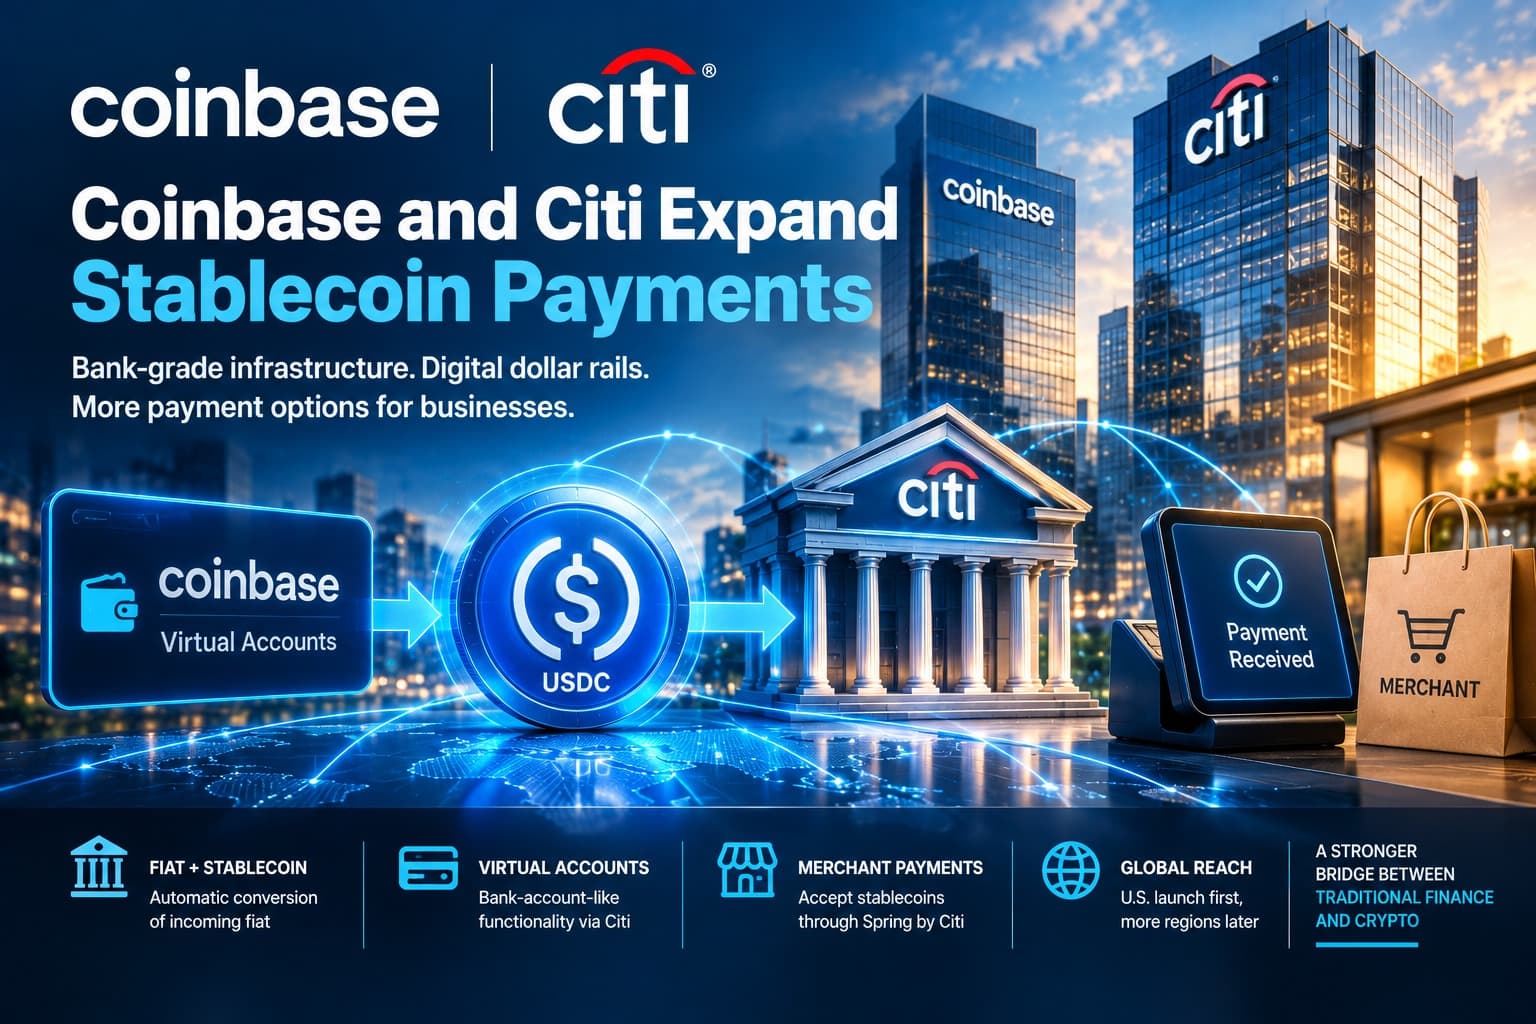
Coinbase and Citigroup are deepening their payments collaboration to connect traditional bank accounts with stablecoin infrastructure, giving businesses new ways to accept, hold and move digital-dollar value without building separate banking and blockchain systems. The expanded relationship combines Coinbase’s digital-asset payment rails with Citi’s regulated banking infrastructure and merchant-acquiring platform.
Announced on September 28, 2026, the initiative has two main components.
First, Coinbase is using Citi’s Virtual Account Wallet to power Coinbase Virtual Accounts, giving businesses bank-account-like functionality for accepting, holding and sending fiat while automatically converting incoming fiat into stablecoins.
Second, Coinbase’s payments infrastructure is being connected to Spring by Citi, allowing Citi’s institutional clients to accept stablecoin payments from customers while receiving settlement in government-issued currency.
 Michael Saylor Proposes a Bill of Digital Rights to Fuel a $100 Trillion Digital Economy→
 BlackRock: AI Will Drive a New Machine-Native Economy→
 Solana Tokenized Stocks Smash Records with 850K Unique Holders and Institutional Adoption→
 How CFOs Are Transforming Corporate Treasury With Digital Assets, XRP, and RLUSD→
The developments represent a different stage of crypto adoption: stablecoins are being integrated into existing corporate payment infrastructure rather than requiring businesses to operate entirely inside the cryptocurrency ecosystem.
From crypto rails to corporate banking
Businesses using digital assets have traditionally faced a practical problem: the banking and blockchain sides of a payment stack often have to be assembled separately.
A company might need a bank account for fiat, a crypto account for digital assets, a payment processor for customer transactions and additional infrastructure for conversion and settlement.
Coinbase and Citi are attempting to compress those functions into a more integrated workflow. Coinbase says the expanded collaboration gives businesses a direct path between traditional finance and digital assets without requiring them to build both infrastructures independently.
That is important because corporate payment systems are usually optimized for reconciliation, treasury management, compliance and predictable settlement rather than cryptocurrency-native workflows.
The new architecture puts blockchain-based value transfer underneath a familiar corporate experience.
How Coinbase Virtual Accounts work
The first part of the collaboration involves Coinbase Virtual Accounts.
Coinbase says it selected Citi’s Virtual Account Wallet, part of the bank’s Banking-as-a-Service offering, to support these accounts. The resulting product is designed to provide bank-account-like functionality, including accepting, holding and paying funds.
One feature highlighted by Coinbase is automatic conversion of incoming fiat into stablecoins.
In practical terms, a business can receive conventional currency while using Coinbase’s digital-asset infrastructure underneath the account.
That creates a bridge between two different forms of money:
Fiat inflow → conversion → stablecoin balance → digital-asset payment or transfer
The benefit is not that the business necessarily needs to expose customers or treasury staff to crypto terminology.
The blockchain-based component can operate as the settlement layer while the user-facing product remains closer to conventional banking.
Stablecoin acceptance through Spring by Citi
The second part of the announcement targets merchants and Citi’s institutional clients.
Spring by Citi is Citi’s digital payment-acceptance platform for merchant acquiring, gateway technology and settlement. Citi describes Spring as an end-to-end digital payments service for ecommerce and B2B flows, with settlement and reconciliation capabilities built into the broader platform.
Under the new Coinbase collaboration, Citi’s institutional clients can accept stablecoin payments at checkout.
The customer pays using a digital currency, while Coinbase’s infrastructure automatically converts the incoming digital asset into fiat. Citi then settles the resulting funds as the bank of record.
This distinction is crucial.
The merchant does not necessarily need to hold stablecoins or manage a crypto wallet.
The customer can use a blockchain-based payment method while the merchant remains exposed to the traditional currency settlement it already understands.
That structure could remove one of the biggest barriers to corporate adoption: the operational burden of managing digital assets directly.
The infrastructure is designed to hide unnecessary complexity
Coinbase executives repeatedly emphasized this aspect of the new system.
Alec Lovett, Coinbase’s Head of Infrastructure Product, said the collaboration is intended to give businesses bank-account-like functionality with stablecoin infrastructure underneath it and allow customers to move between fiat and digital assets without needing to distinguish which rail is being used.
Brett Tejpaul, Head of Coinbase Institutional, described Citi as the type of regulated banking partner that can help move digital assets from experimentation toward everyday commerce.
These are company statements and should be understood as Coinbase’s characterization of the partnership rather than independent assessments.
Nevertheless, they identify an important product-design philosophy.
Mainstream financial infrastructure rarely succeeds by asking businesses to learn an entirely new operational model.
Instead, new technology tends to succeed when the complexity is handled behind familiar interfaces.
Citi’s role is broader than settlement
Citi’s role matters because the bank already operates a large global payments infrastructure.
Citi says its network serves clients in more than 180 countries and jurisdictions, with a physical presence in more than 90 markets. The bank also describes its payments business as operating across domestic and cross-border payment networks.
Spring by Citi is designed to support digital payment acceptance, funds settlement, reconciliation and reporting.
That means the Coinbase collaboration is not simply a crypto-to-fiat conversion service.
It places stablecoin functionality inside an existing merchant-acquiring and treasury environment.
For large companies, that distinction can matter more than the blockchain itself.
Corporate finance teams need payment records, reconciliation, accounting data, settlement instructions and predictable banking relationships.
A stablecoin rail becomes more useful when it can operate within those existing processes.
The companies have been building toward this partnership
The September announcement is an expansion of a relationship that began in October 2025.
At that time, Coinbase and Citi announced a collaboration focused on helping Citi clients use digital assets and stablecoins for payments, treasury management and financial infrastructure. Coinbase described the work as including on- and off-ramps and stablecoin payment solutions.
The earlier collaboration established the basic architecture.
The new arrangement moves toward specific commercial applications.
Instead of simply studying how banks could interact with blockchain assets, the companies are now connecting:
bank accounts + stablecoins + merchant acceptance + fiat settlement.
That progression is significant because enterprise adoption generally depends on practical workflows rather than technology demonstrations.
Expert opinions: the banking relationship is the important part
Citi’s Debopama Sen, Head of Payments, said the bank’s objective is to build payment infrastructure that can operate across both traditional and digital payment instruments and networks.
That statement reflects the broader evolution of institutional crypto infrastructure.
Banks do not necessarily need to replace existing payment systems with blockchains.
They can instead add digital-asset rails alongside conventional banking networks.
This approach also mirrors Citi’s wider 2026 strategy. During its May Investor Day, Citi executives said clients were increasingly asking what blockchain technology could do to improve the movement of money, payments and working-capital management, while noting that the bank remained open to stablecoin use cases as demand developed.
That suggests the stablecoin question for large banks has become increasingly practical:
Where can blockchain improve an existing financial workflow?
What this means for merchants
The new acceptance model could reduce several operational barriers for enterprise merchants.
A conventional merchant wants to receive customer payments and reconcile them with its accounting system.
With the Coinbase-Citi arrangement, a customer can pay using a stablecoin, Coinbase can handle the digital-asset conversion, and Citi can deliver fiat settlement to the merchant.
That potentially creates several benefits.
Currency flexibility
Customers can use a digital-dollar payment rail while the merchant receives fiat.
Reduced crypto exposure
The merchant does not necessarily need to maintain a stablecoin treasury balance.
Existing settlement infrastructure
The merchant can remain connected to a banking relationship rather than building an independent crypto cash-out system.
Potentially global architecture
Citi’s international footprint provides a foundation for future geographic expansion, although Coinbase explicitly says the current initiatives launch first in the United States.
These potential benefits still need to be demonstrated through actual transaction volumes and enterprise adoption.
Stablecoins are becoming a payment layer, not only a crypto asset
The Coinbase-Citi announcement is part of a larger change in how stablecoins are being positioned.
Coinbase says its payments infrastructure processes substantial stablecoin activity and has been expanding integrations with banks, payment providers and merchants.
The exchange has also recently partnered with Stablecore to provide community and regional banks and credit unions with digital-asset services, including stablecoin payments, through their existing banking platforms.
Earlier in September, Coinbase and Moov announced stablecoin payment acceptance, settlement and real-time funding for a network serving more than 1,000 community banks and credit unions.
Taken together, these partnerships indicate a broader strategy.
Coinbase is increasingly positioning its infrastructure as a layer that banks, fintech companies and merchants can use without building blockchain systems themselves.
Why automatic conversion matters
Automatic conversion addresses a fundamental mismatch between digital-asset payments and corporate accounting.
A merchant selling goods in dollars generally does not want its revenue to fluctuate because the value of a cryptocurrency changes.
Stablecoins reduce that volatility, but merchants may still prefer to receive conventional bank money.
The conversion model solves both problems:
Customer: pays with a digital-dollar asset.
Payment infrastructure: processes and converts the digital payment.
Merchant: receives fiat settlement.
This model resembles card processing more closely than a conventional crypto transaction.
It also explains why the involvement of a global bank matters.
Citi provides the regulated banking and settlement layer while Coinbase provides the digital-asset infrastructure.
Regulatory and operational considerations remain
The integration does not remove the regulatory requirements attached to payments.
Citi’s broader payment infrastructure includes compliance, settlement and reporting processes, while Coinbase operates its digital-asset infrastructure within applicable regulatory frameworks.
Businesses will still need to consider:
- customer and business verification;
- sanctions screening;
- accounting treatment;
- tax reporting;
- transaction monitoring;
- stablecoin issuer risk;
- geographic availability;
- banking and payment regulations.
The fact that a stablecoin payment is converted into fiat does not eliminate those responsibilities.
Nor does a bank partnership mean every company or jurisdiction will receive immediate access to the same services.
Coinbase says the new initiatives will launch first in the United States, with additional capabilities expected in the following months.
The connection to AI-agent payments
There is also a connection between this development and the emerging market for AI-agent payments.
Coinbase has already integrated x402 into its business payments infrastructure, allowing businesses to accept payments from AI agents. The company says its Business payments suite can receive agent payments in USDC and settle those funds into business accounts.
That suggests a potential future payment stack:
Human customer → stablecoin → merchant
and
AI agent → stablecoin → API or merchant
The two models use similar digital settlement infrastructure even though their users are different.
CryptoQuorum recently examined this wider convergence in its coverage of BlackRock’s Machine-Native Economy, where stablecoins are discussed as potential machine-to-machine settlement instruments.
The Citi collaboration therefore has potential relevance beyond conventional ecommerce.
How this fits CryptoQuorum’s stablecoin coverage
The partnership also connects directly with several developments already reshaping the stablecoin market.
Zebec and MoneyGram, for example, are combining stablecoin payroll on Stellar with local-currency cash access through MoneyGram’s network.
Ripple’s RLUSD strategy focuses on regulated issuance, reserve structures and institutional settlement.
These projects address different problems, but the underlying trend is similar:
Stablecoins are increasingly being connected to existing financial infrastructure rather than operating as isolated crypto instruments.
That transition could make payment use cases more important for the digital-asset sector than speculative trading alone.
What to watch next
The most important evidence will come from actual deployment.
Enterprise adoption
The number and size of Citi clients using the new acceptance infrastructure will show whether demand is strong.
Payment volume
Transaction growth will indicate whether businesses are actually using stablecoins at checkout.
Fiat settlement efficiency
The value proposition will depend partly on how smoothly digital payments can be converted and settled through traditional banking infrastructure.
Geographic expansion
The current launch is U.S.-first. Future expansion will test whether the model can operate across different regulatory and payment environments.
Additional bank integrations
Coinbase’s partnerships with Citi, Stablecore and Moov suggest that bank connectivity is becoming a central part of its payments strategy.
AI commerce
Growing usage of agentic payments could provide another source of demand for programmable digital settlement.
Bottom line
The expanded Coinbase-Citi relationship marks a significant step in the integration of stablecoin payments with conventional banking infrastructure.
Coinbase Virtual Accounts use Citi’s Virtual Account Wallet to provide bank-account-like functionality with stablecoin conversion underneath, while Citi’s institutional clients can use Spring by Citi to accept stablecoin payments and receive fiat settlement through the bank.
The structure is important because businesses do not necessarily have to choose between traditional banking and digital assets.
They can use both.
Coinbase provides the blockchain and stablecoin infrastructure. Citi provides banking, merchant acceptance and settlement capabilities. The current rollout begins in the United States, with additional capabilities expected later.
The broader significance is the normalization of stablecoins as payment infrastructure.
This does not mean traditional banking rails are disappearing. The model being developed by Coinbase and Citi is instead based on integration: blockchain settlement operates underneath familiar bank accounts, merchant processing and fiat settlement.
That approach could become increasingly important as businesses look for faster, programmable and globally accessible payment infrastructure without assuming the operational burden of becoming crypto-native institutions.
The next test will be real-world usage.
If large corporate merchants begin accepting stablecoins at meaningful scale while continuing to settle in fiat through established banking infrastructure, the Coinbase-Citi model could become a useful template for how digital assets are incorporated into mainstream commerce.
Disclaimer
This article is provided for informational and educational purposes only and does not constitute financial, investment, legal, tax, accounting or other professional advice. Stablecoins and digital-asset payment systems involve regulatory, counterparty, operational, cybersecurity and liquidity risks. Availability of Coinbase and Citi services may vary by jurisdiction, client eligibility and applicable regulations. References to potential benefits describe the intended use cases of the announced infrastructure and do not guarantee cost savings, adoption or financial performance. Readers and businesses should conduct independent due diligence and consult qualified professionals before making financial decisions.