

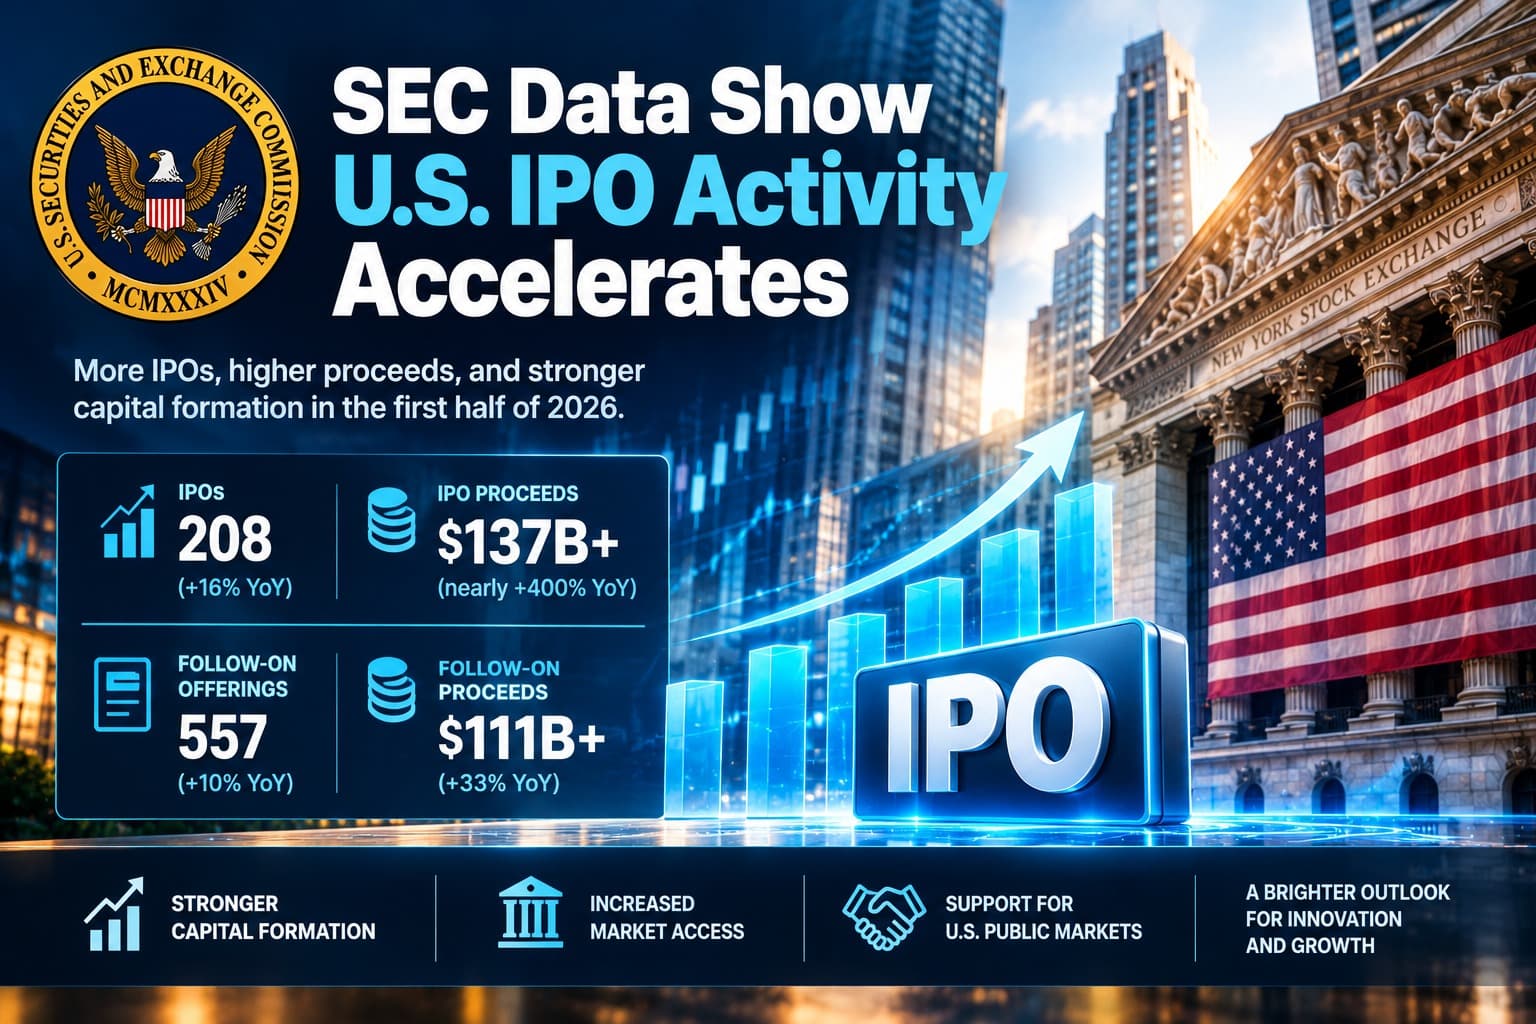
U.S. IPO activity accelerated sharply in the first half of 2026, with 208 initial public offerings raising more than $137 billion, according to updated statistics published by the U.S. Securities and Exchange Commission. The number of IPOs increased by about 16% from the same period in 2025, while proceeds rose by nearly 400%.
The data, published on September 23 by the SEC’s Division of Economic and Risk Analysis (DERA), also show stronger follow-on issuance. There were 557 follow-on registered offerings in the first half of 2026, raising more than $111 billion, compared with 505 offerings that raised nearly $84 billion during the first half of 2025.
The figures provide one of the clearest snapshots so far of the state of U.S. public-market capital formation in 2026.
They also fit into a broader SEC agenda aimed at making public markets more accessible to companies while updating reporting and offering requirements.
 Robinhood’s Evolving Wealth Management Strategy Targets the Future of Retail Investing→
 Fed Rate Hike May Not Rattle Crypto Markets, Grayscale Says→
 Solana Tokenized Equity Supply Surges to Record $684M Amid Multi-Platform Expansion→
 XRP Ledger Foundation Advances Ecosystem Resilience with Strategic Infrastructure Upgrades→
IPO proceeds are rising much faster than deal count
The most notable feature of the data is the gap between the growth in the number of IPOs and the growth in capital raised.
The number of deals increased from 180 in H1 2025 to 208 in H1 2026, a rise of roughly 16%. Proceeds, however, increased from more than $27 billion to more than $137 billion. The SEC characterizes that as a nearly 400% increase.
In other words, the public market is not simply seeing more companies list.
It is also raising substantially more money per offering across the aggregate market.
That distinction matters because a rise in proceeds can come from several factors: larger individual deals, stronger demand for newly listed shares, or a greater concentration of issuance among larger companies.
The SEC’s headline statistics do not, by themselves, identify which of these factors accounts for the entire increase.
They do show that the capital value of the IPO market has expanded much faster than the number of transactions.
A much stronger comparison with 2025
The scale of the change becomes clearer when the first-half periods are compared directly.
| Market segment | H1 2025 | H1 2026 | Year-over-year change |
|---|---|---|---|
| IPOs | 180 | 208 | ~16% increase |
| IPO proceeds | >$27B | >$137B | Nearly 400% increase |
| Follow-on offerings | 505 | 557 | ~10% increase |
| Follow-on proceeds | ~$84B | >$111B | ~33% increase |
Source: SEC Division of Economic and Risk Analysis. The SEC notes that its statistics are produced from commercial datasets supplied by third parties and may change as data and methodologies are revised. (SEC)
The comparison suggests that the recovery in public fundraising is broad rather than limited to initial listings alone.
Follow-on registered offerings also increased, although at a much more moderate rate than IPO proceeds.
That matters because follow-on issuance provides a separate measure of whether already-public companies are actively accessing equity markets.
What the numbers say about capital formation
Capital formation refers broadly to the process through which businesses obtain financing that can be used for investment, expansion, acquisitions, operations and other corporate purposes.
Public equity markets are one component of that system.
The new SEC data show that companies raised significantly more capital through public offerings in the first six months of 2026 than during the comparable period in 2025.
SEC Chief Economist and DERA Director Joshua T. White said the updated statistics demonstrate continued strengthening in U.S. capital formation and are intended to provide market participants and policymakers with transparent data on market conditions.
The SEC has also emphasized that its data tools are designed to let users examine market trends through time-series charts, distributions and geographic visualizations.
That transparency is relevant because headline figures can conceal significant differences between sectors, issuers and individual deals.
The data come with an important methodological caveat
The SEC’s statistics should not be treated as a perfectly complete census of every U.S. capital-raising transaction.
On its IPO statistics page, the agency states that the figures are produced from commercial datasets provided by third parties. The SEC says its staff cannot guarantee the accuracy of those third-party datasets and that the statistics may change when data or methodology are revised.
That caveat is important for financial reporting.
The numbers are official SEC-published statistics, but the underlying data methodology means that historical values can be revised.
For readers comparing different market reports, the appropriate approach is therefore to use the SEC’s latest published dataset and avoid treating a preliminary figure as permanently fixed.
Follow-on offerings add another positive signal
The second major development is the increase in follow-on registered offerings.
Companies completed 557 such offerings in the first half of 2026, compared with 505 in the first half of 2025. Proceeds increased from nearly $84 billion to more than $111 billion.
That represents roughly a 10% increase in the number of offerings and a 33% increase in capital raised.
The comparison with IPOs is instructive.
IPO issuance measures companies entering the public market through an initial registered offering. Follow-on issuance measures companies that are already public returning to registered markets for additional capital.
When both categories grow at the same time, the data provide a broader indication that public equity financing is active across different stages of the corporate lifecycle.
The SEC is pursuing a broader public-market reform agenda
The September statistics come several months after the SEC proposed significant changes to the rules governing registered offerings and public-company reporting.
In May, the Commission proposed reforms designed to increase access to public capital markets, expand eligibility for shelf-registration and offering flexibilities, and simplify parts of the reporting framework. The proposal also included changes intended to extend scaled disclosure accommodations to a substantially larger share of public companies.
The SEC said those reforms were intended in part to encourage more companies to go and stay public.
That policy direction provides useful context for the latest data.
There is a distinction between a market experiencing stronger issuance and a regulatory system deliberately attempting to increase access to public markets.
The September statistics show what is happening in the market.
The May proposals show what the SEC is trying to change about the market structure.
Expert opinion: the SEC sees public-market data as a policy tool
The SEC’s chief economist has emphasized that market statistics are not simply retrospective reporting.
DERA’s role is also to provide economic and statistical analysis that informs SEC rulemaking and oversight.
That matters because the agency is currently considering a number of changes affecting companies at different stages of the public-market lifecycle.
SEC Chairman Paul Atkins has separately said that revitalizing public markets is a central part of the Commission’s agenda, including reforms designed to reduce compliance burdens while maintaining investor protections.
The two positions are complementary.
DERA provides the data used to understand market conditions, while the Commission considers regulatory changes intended to influence how efficiently companies and investors interact with those markets.
The latest IPO figures therefore have relevance beyond a single quarterly statistic.
Why larger offerings matter
The much faster increase in proceeds than deal count raises an important market-structure question: are companies simply raising more capital per listing?
The SEC’s headline release does not break down the $137 billion by individual issuer size or explain how much of the increase comes from exceptionally large deals.
But the arithmetic is revealing.
With just 16% more IPOs and nearly 400% more proceeds, the average capital raised per IPO was substantially higher in H1 2026 than H1 2025.
Using the SEC’s approximate figures, average proceeds per IPO moved from roughly $150 million to about $659 million.
That calculation is only an approximate comparison because the SEC describes the historical totals as “over” or “nearly” specific amounts.
Nevertheless, the direction is clear: the increase in capital raised cannot be explained by the increase in deal count alone.
For investors, that means the composition of the IPO pipeline matters as much as the number of companies coming public.
What stronger IPO activity markets mean for digital assets
The connection to the crypto industry is indirect but increasingly relevant.
More active public-equity markets can improve the environment for companies operating in digital assets, blockchain infrastructure, financial technology and tokenization that eventually seek public-market financing.
The trend is particularly relevant as traditional securities infrastructure itself becomes more digital.
CryptoQuorum recently covered the SEC’s Innovation Exemption for tokenized NMS stock, which establishes a temporary framework for certain on-chain trading venues to trade tokenized U.S. equities.
That development sits alongside DTCC’s tokenization initiative, which is moving toward an October 2026 launch after production testing of tokenized DTC-custodied securities.
Taken together, these developments show two different layers of market evolution.
One concerns how companies raise capital and become public.
The other concerns how securities may eventually be issued, represented, transferred or traded using blockchain infrastructure.
The two trends are not the same, but they increasingly intersect within the broader modernization of financial markets.
IPO access is only one part of the public-market ecosystem
A stronger IPO market does not automatically mean that all companies have easier access to capital.
Companies still need suitable market conditions, investor demand, underwriters, viable business models and sufficient scale to complete a public offering.
The SEC’s May proposal acknowledges that regulatory costs and disclosure requirements can influence a company’s decision to remain private or enter the public markets.
The current statistics therefore represent an outcome, not a guarantee of continued momentum.
A rise in issuance can reverse if financing conditions deteriorate, valuations fall or investor risk appetite changes.
For that reason, one strong first-half period should be viewed in the context of longer-term market data.
The SEC’s interactive statistics are useful here because they allow investors to compare historical issuance across multiple years rather than relying only on a single headline figure.
What to watch in the second half of 2026
Several indicators will help determine whether the stronger first-half figures continue.
IPO pipeline
The number of newly filed and completed IPOs will indicate whether issuance momentum is broadening or fading.
Average deal size
Because proceeds are growing much faster than transaction counts, the average size of offerings deserves particular attention.
Follow-on issuance
Continued growth would suggest that already-public companies are also finding the equity market accessible.
Investor demand
The performance and trading liquidity of newly listed companies can affect the willingness of future issuers to enter public markets.
Regulatory implementation
The SEC’s proposed offering and reporting reforms could influence the costs and incentives associated with remaining public.
Digital-market infrastructure
For crypto and tokenization companies, developments in regulated market access, tokenized securities and institutional settlement could expand the range of financing and trading models available in the future.
What the SEC data do not tell us
The latest statistics are useful, but they have limits.
They do not by themselves establish that the U.S. IPO market has entered a permanently stronger cycle.
They also do not show whether all sectors or company sizes experienced the same degree of improvement.
Nor do the numbers tell investors whether individual IPOs were priced attractively or whether newly public companies subsequently outperformed the wider market.
Those are separate analytical questions.
The SEC data establish capital-raising volume and transaction counts. Additional market data are required to evaluate valuation, post-IPO performance and sector composition.
Keeping those distinctions clear is important when interpreting a strong headline statistic.
Bottom line
The latest SEC data show a substantial increase in U.S. public-market fundraising during the first half of 2026.
There were 208 IPOs raising more than $137 billion, compared with 180 IPOs raising more than $27 billion in H1 2025. Follow-on registered offerings also increased, reaching 557 transactions and more than $111 billion in proceeds.
The most important feature is the divergence between transaction growth and capital growth.
A roughly 16% increase in IPO count was accompanied by a nearly 400% increase in proceeds, indicating that the market raised substantially more capital per transaction in aggregate.
The SEC views these numbers as evidence of stronger capital formation, while its broader 2026 agenda includes reforms intended to make public offerings and reporting more efficient.
For CryptoQuorum readers, the development also provides an important backdrop for the growing intersection of traditional public markets and blockchain infrastructure. SEC work on tokenized securities and DTCC’s development of tokenized custody and settlement systems show that the modernization of capital markets is happening on several fronts at once.
The next question is whether the unusually strong increase in proceeds continues through the second half of 2026 – and whether a broader range of companies can access the public markets under the evolving regulatory framework.
Disclaimer
This article is provided for informational and educational purposes only and does not constitute financial, investment, legal, tax or other professional advice. The SEC statistics are staff-produced data based in part on commercial third-party datasets and may be revised as data or methodologies change. Historical issuance figures do not predict future IPO activity, company performance or investment returns. Readers should conduct independent research and consult qualified professionals before making financial or investment decisions.