

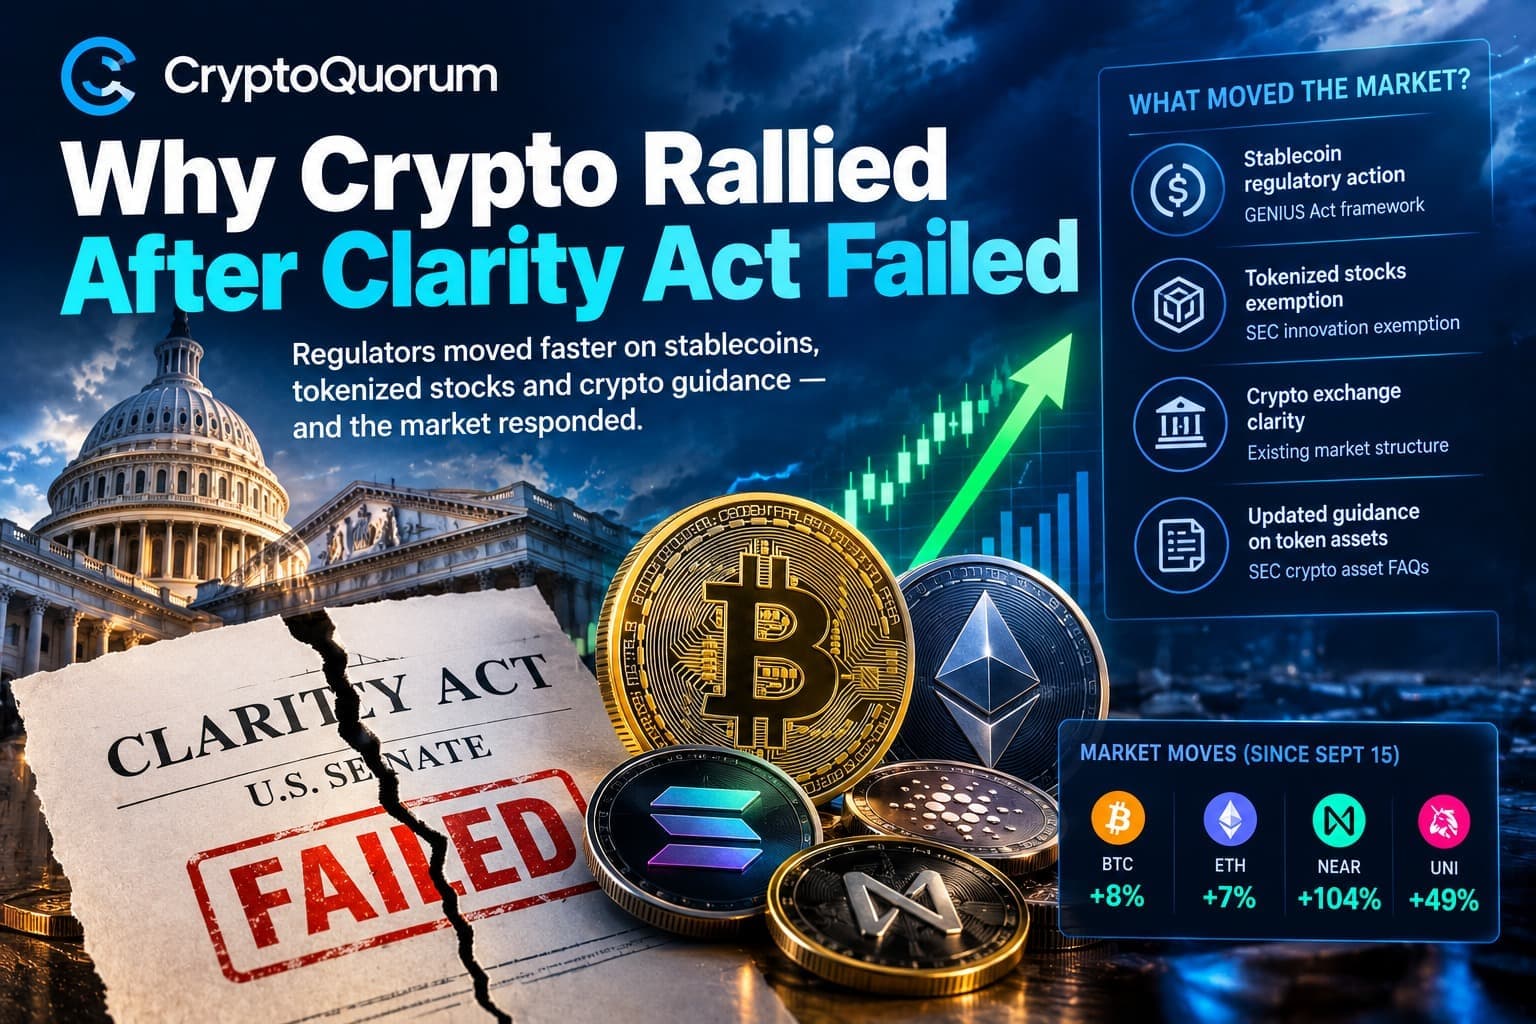
The U.S. Senate’s failure to advance the Clarity Act on September 15 did not produce the sustained crypto-market weakness that some investors might have expected from the collapse of a major regulatory initiative.
Instead, according to Bitwise Chief Investment Officer Matt Hougan, the market rallied sharply in the two weeks following the vote. In his September 30 CIO Memo, Hougan reported that Bitcoin had gained 8% and Ethereum 7% since the vote, while several other crypto assets posted much larger increases, including NEAR at 104%, Uniswap at 49% and Avalanche at 43%. These figures reflect the period covered by Bitwise’s memo rather than a forecast of future performance.
BINANCE:BTCUSDT
Hougan’s explanation is not that regulation has become irrelevant. Instead, he argues that the failure of a comprehensive bill may have reduced the time required to resolve some narrower regulatory questions because U.S. agencies subsequently moved using existing authority.
That distinction is important. Legislation can provide a more durable statutory framework, while agency guidance, exemptions and interpretations can generally be changed or replaced more easily.
 Coinbase and Citi Expand Stablecoin Payments for Businesses→
 CFTC Clarifies Tokenized Collateral Rules and On-Chain Recordkeeping→
 Brazil Crypto Regulation Tightens as Self-Custody Reporting Expands→
 SEC Data Show U.S. IPO Activity Accelerates in First Half of 2026→
What happened to the Clarity Act?
On September 15, the Senate failed to advance the Clarity Act in a 50-49 procedural vote. The legislation needed 60 votes to advance. Reuters reported that four Republicans joined Democrats in voting against the measure.
The bill sought to establish a broader federal regulatory framework for digital assets, including defining the roles of the Securities and Exchange Commission and Commodity Futures Trading Commission.
The failure followed years of negotiations and was widely watched because crypto companies had treated the legislation as an important route toward greater legal certainty.
Hougan’s analysis takes a different angle: rather than focusing only on what the bill would have established, he examines what happened in the days immediately after its failure.
1. Stablecoin rewards remain an open area
One issue addressed in Hougan’s memo is the treatment of stablecoin interest and rewards.
He argues that negotiations over the legislation resulted in restrictions that would have prevented platforms from paying customers stablecoin interest or yield under the proposed framework. Because the bill did not advance, that provision did not become federal law.
The existing GENIUS Act remains the federal statutory framework for payment stablecoins. President Donald Trump signed the law on July 18, 2025, establishing federal requirements for qualifying payment-stablecoin issuers.
Hougan’s interpretation is that the enacted framework prohibits interest payments by issuers but leaves more room for exchanges and platforms to structure customer reward programs.
This is an important distinction: a stablecoin issuer and a trading platform do not necessarily play the same legal or economic role. The structure of any individual rewards program therefore matters.
For the market, the unresolved question is how regulators will treat different forms of compensation attached to stablecoin balances as products evolve.
2. Crypto exchanges keep their existing structure
Hougan also focuses on cryptocurrency exchanges.
His memo argues that the proposed legislation could have introduced a national licensing framework for spot crypto exchanges while also imposing restrictions on the combination of exchange and brokerage functions.
The U.S. crypto market currently operates through a more fragmented regulatory structure, with firms navigating multiple state and federal requirements. Hougan contends that preserving the existing framework can give established exchanges an advantage because competitors still face substantial regulatory and operational barriers.
This is his market-structure interpretation, not an official government finding about the competitive position of any particular exchange.
The broader issue is whether future regulation will consolidate crypto-market rules at the federal level or continue to develop incrementally through agencies, states and enforcement actions.
3. Tokenization moved faster than legislation
The clearest example in Hougan’s argument concerns tokenized securities.
Two days after the Senate vote, on September 17, the SEC issued a temporary, conditional exemption allowing certain permissioned venues to facilitate trading in tokenized NMS stocks through automated market makers and liquidity pools. The order also provides a related exemption for certain liquidity providers from the statutory definition of a dealer.
The exemption is limited. It applies to defined tokenized U.S. stocks, operates under conditions set by the SEC and is temporary. The Commission is also seeking public comment as it evaluates the framework.
SEC Chairman Paul Atkins described the action as a way to permit onchain trading of certain tokenized stocks while the Commission considers additional steps. Commissioner Mark Uyeda said tokenization could modernize functions such as issuance, trading, settlement and ownership records, while emphasizing the temporary and experimental nature of the exemption.
This development directly connects with CryptoQuorum’s earlier coverage of the SEC Innovation Exemption for tokenized NMS stock and the DTCC Tokenization Service.
Hougan’s point is that a legislative mandate to study tokenized securities could have taken considerably longer to translate into live market experimentation. The SEC instead created a temporary framework using its existing authority.
That does not mean the permanent regulatory question has been resolved. It means experimentation began before Congress enacted a comprehensive statute.
4. Revenue-generating tokens received clearer SEC guidance
Another part of Hougan’s analysis concerns crypto assets associated with protocol revenue and token buybacks.
He highlights assets such as Hyperliquid, NEAR, Uniswap, Lighter and Pump, noting that several had risen substantially during the period covered by his memo. His argument is that questions surrounding token buybacks could have remained uncertain under a new statutory framework.
The SEC subsequently addressed the issue through its published crypto-asset FAQs.
The Commission states that where a crypto system is functional and has no central party, an issuer’s announcement of a buyback program for a non-security crypto asset would not constitute a representation or promise to undertake essential managerial efforts. The SEC distinguishes this situation from an arrangement in which the system is not functional and communications about buybacks may be connected to expectations of returns.
That guidance does not create blanket regulatory immunity for all token buybacks. The surrounding facts and structure remain relevant.
Still, it demonstrates the mechanism Hougan identifies: some uncertainty can be addressed through agency interpretation without waiting for Congress to pass a new statute.
What Hougan sees as the trade-off
Hougan’s central argument is that the crypto industry may have exchanged long-term statutory certainty for faster regulatory experimentation.
He describes the result as favorable for the market because several regulators have recently issued guidance or exemptions that address practical questions more quickly than a comprehensive legislative process might have done.
That is an opinion from Bitwise’s CIO rather than an established conclusion about the overall value of the legislative outcome.
There is also a substantial counterpoint.
A law passed by Congress can create a statutory framework that survives changes in agency leadership more easily than guidance or temporary exemptions. Hougan himself identifies this as the major risk in his memo, noting that agency interpretations are potentially vulnerable to future changes in administration and regulatory policy.
The distinction between speed and durability is therefore central to the debate.
Why the market response matters
The unusual market reaction provides a useful case study in how digital assets respond to regulatory developments.
The immediate interpretation after the Senate vote was not necessarily the same as the interpretation two weeks later. Bitwise’s data shows that several major crypto assets recovered or advanced despite the legislative setback.
However, a market rally alone does not demonstrate that investors believe the legislative failure is permanently beneficial. Prices incorporate many variables, including liquidity, macroeconomic expectations, positioning, technology developments and expectations about future regulation.
The more concrete development is the acceleration of regulatory action in specific areas.
Stablecoin rules already exist through the GENIUS Act. The SEC has introduced a temporary framework for certain tokenized stock venues. The SEC has also published additional guidance on the application of securities laws to crypto assets.
These actions do not replace comprehensive market-structure legislation. They represent a different regulatory pathway.
What happens next for U.S. crypto regulation?
The next stage is likely to be shaped by whether Congress eventually returns to comprehensive legislation or whether agencies continue addressing individual market segments through rules, exemptions, interpretations and enforcement.
For tokenization, the SEC’s temporary framework and the planned expansion of institutional infrastructure are particularly relevant. CryptoQuorum’s coverage of DTCC’s tokenization program shows how traditional market infrastructure is simultaneously preparing for blockchain-based securities.
Stablecoins are another major area to watch. The GENIUS Act has created a federal framework for qualifying payment stablecoin issuers, while companies such as Coinbase and banks such as Citi are building infrastructure around stablecoin payments. CryptoQuorum recently covered the Coinbase-Citi stablecoin payments initiative.
Together, these developments suggest that U.S. digital-asset regulation is not moving along a single track.
Congress can create statutory rules. Agencies can interpret existing law. Regulators can introduce temporary exemptions to test new technologies. Market participants can build products within those boundaries.
The result is a regulatory environment that may change incrementally even when major legislation stalls.
The bigger picture
Matt Hougan’s September 30 memo offers one explanation for why crypto prices rose after an important legislative setback. His thesis is that the absence of a comprehensive bill removed some negotiated restrictions while allowing regulators to address several practical issues more quickly.
The documented developments support part of that chronology, particularly the SEC’s September 17 tokenized-stock exemption and its updated crypto-asset FAQs.
But the longer-term consequences remain uncertain.
A statutory market-structure law could provide forms of legal certainty that temporary exemptions and agency interpretations cannot fully replicate. Conversely, incremental regulatory action can move faster and allow regulators to gather real-world data before establishing permanent rules.
For crypto markets, the key question may therefore be less about whether regulation arrives and more about which regulatory mechanism arrives first, how durable it is, and how the market adapts to it.
Disclaimer
This article is for informational purposes only and does not constitute investment, legal, tax or financial advice. Market movements cited from the Bitwise CIO Memo refer to the period specified in that publication and should not be interpreted as forecasts or guarantees. Regulatory frameworks can change, and readers should consult primary sources and qualified professional advisers when evaluating legal or investment issues.